Instead of Thai Food, Jewelry
A jewelry store called The Missing Link will take half the space formerly occupied by Spice at University and 10th.
Here, in its entirety, is a recent New York Times article about maintenance increases and transfer fees and how co-ops are currently suffering.
Co-op Fees Go Through the Roof
CO-OPS across the city have raised their maintenance charges by as much as 15 percent in recent months, and one of the main causes is rising property taxes.
Board members and building managers say that while maintenance increases averaged only about 5 percent last year, many co-op buildings are now dealing with double-digit increases.
“Operating costs have gone up, but property taxes have skyrocketed,” said John Janangelo, the president of Bellmarc Property Management, which manages about 50 apartment buildings in Manhattan. He said that taxes for some of his buildings had risen by as much as 35 percent in 2009. “It comes at the worst time,” he added, “because financially everyone is suffering. You don’t want to pass through these huge increases because people can’t afford them, but you have no choice.”
Property taxes went up at the start of the year when the city eliminated a 7 percent homeowner tax cut initiated in 2007, when the city was on better financial footing. But there is another reason for the increase. Buildings whose property values soared in recent years are experiencing even bigger tax increases because the assessed values of their buildings have gone up.
Co-op boards routinely challenge their assessments and if the city’s Tax Commission does not reduce the assessments, boards can appeal in court. Because the process is lengthy, a building that has received a series of big assessment increases may not get relief for years.
“Assessments have gone up based on last year’s market,” said David Kuperberg, the president of Cooper Square Realty, which manages about 200 co-ops and condominiums. “And that’s like kicking homeowners while they’re down,” he added, noting that assessments often take a while to catch up to the market.
Marty Hoffman, the board treasurer of a 106-unit co-op on West 89th Street, said that the assessed valuation of the building had gone up every year in the last five years for a total increase of 107 percent. The property tax bill has gone up 55 percent, from $369,000 in 2004 to $574,000 in 2009. Taxes this year alone went up by $83,000, or roughly $783 more annually for each tenant shareholder.
Because each year’s higher assessment is phased in over a five-year period, Mr. Hoffman’s building faces at least four more years of hefty assessment increases as the increases that were issued when the market was booming continue to kick in. Mr. Hoffman said that even though the tentative assessment increase for 2009-10 was only 1 percent, the building may have another tax increase of about $83,000 next year because of the phase-in of previous assessment increases. “Aside from the run-up in oil prices,” he said, “nothing has gone up as fast as real estate taxes.”
Mr. Hoffman said cheaper fuel was the only reason his building had been able to limit its annual maintenance fee increase to 7.2 percent. “If oil prices hadn’t dropped, we would have been faced with a 15 percent increase.”
Some operating costs have risen, however. Richard Montanye, a partner with the accounting firm of Marin & Montanye in Uniondale on Long Island, which works with hundreds of buildings in the city, said that water and sewerage charges went up 14.5 percent last year. “Housing costs in the city in the past four to five years have far outpaced inflation,” he said.
At the same time, some revenue sources have been drying up for many buildings. Those with commercial tenants, especially retail outlets, have been hit hard by the recession, with many tenants asking for rent reductions because their sales volume has dropped off significantly.
“Retail tenants are all hurting,” said Richard Siegler, a lawyer who represents about 150 co-ops, “and they’re all coming to boards and asking for relief. If the economy improves, then a lot of this will go by the by, but if not, then boards will have to contemplate losing tenants, even though they’d rather not have a vacancy.”
Buildings that in a stronger market relied on income from flip taxes — a sort of transfer fee for each sales transaction — may also struggle now that sales volume throughout the city has been reduced to a trickle.
Robert Berliner’s 277-unit building on Sutton Place has a 2 percent flip tax for outside buyers, which he said “was a pretty significant source of revenue in 2006 and 2007.” The building had used that income to meet operating costs, but because there are now so few apartments changing hands in the building, the board has shifted its flip tax revenue into its reserve fund. “We’re trying to be more realistic and more conservative in dealing with our budget,” he said.
Mr. Berliner said that because real estate taxes are so high for the building, the board may consider raising the flip tax to 3 percent. Property taxes were just under $3 million last year and represented the single largest expense in the building’s $7 million budget.
Mr. Berliner, who is the co-op’s board treasurer, said that the city raised the building’s assessment by 25 percent in 2008, but the building challenged the increase and got it reduced to 10 percent.
“But when you consider the state of the economy and what’s happening in real estate values,” he said, “how the city could have come up with any increase in assessed valuation is beyond me.”
A tempting lineup of sandwiches awaits at the compact new Make Sandwich shop from Spencer Rubin, who owns the Melt Shop chain. He hired Josh Sharkey, the founder of Bark Hot Dogs, as culinary director. The nine preset sandwich combinations, like tri-tip steak with salsa verde, range in price from $7.95 to $11.95. All sandwiches are made to order in five to seven minutes with ingredients like Parmigiano-Reggiano, organic eggs and Pain d’Avignon bread. You can devise your own from a long list of choices for $10.95, with extra charges for some toppings: Make Sandwich, 135 Fourth Avenue (at 14th Street), 212-398-2602, makesandwich.com.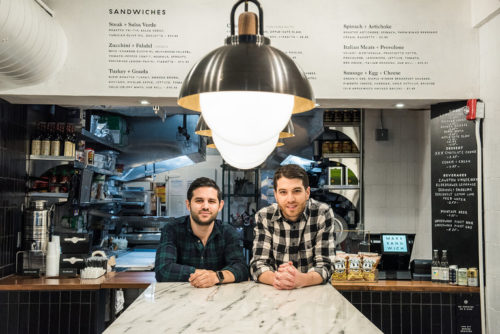
The newest Citibank branch, at 14th and Broadway, is supposed to be a “flagship” and a model for future bank brances, with hotel-lobby-like amenities and a clubby feeling. Enjoy.
NYU is slowly but steadily revealing more of its ultimate expansion plans for completion by 2031. They’re epic in scope, and while most of the activity remains below 8th Street, there’s always the chance that their desire to grow will have them heading our way, as if we didn’t already have enough of that going on. Here’s the plan.
 test
Care to opine about how you feel about Union Square issues?
Take the Union Square Partnership’s 10-minute survey, and you will be entered into a raffle to win a $50 gift card to a local business of your choice.